Why the US Treasury Isn’t Buying Bonds Indiscriminately: The Real Purpose of Buybacks
Summary
- The US Treasury said its buyback program is intended to improve trading in older Treasuries and manage cash efficiently, not to directly lower long-term interest rates.
- High US Treasury yields affect the stock market through corporate valuation and interest expense, meaning investors should also examine a company’s debt size, maturity profile and mix of fixed- and floating-rate borrowing.
- Korean investors buying US bonds and stocks should assess interest rates alongside won-dollar exchange-rate risk, and consider a range of yield scenarios tied to inflation and the US government’s borrowing needs.
Forecast Trend Report by Period

This article appeared on Hankyung Premium 9, the Korea Economic Daily’s paid investment platform. Subscribers to Hankyung Premium 9 can find more stock-investment stories at www.hankyung.com/premium9.
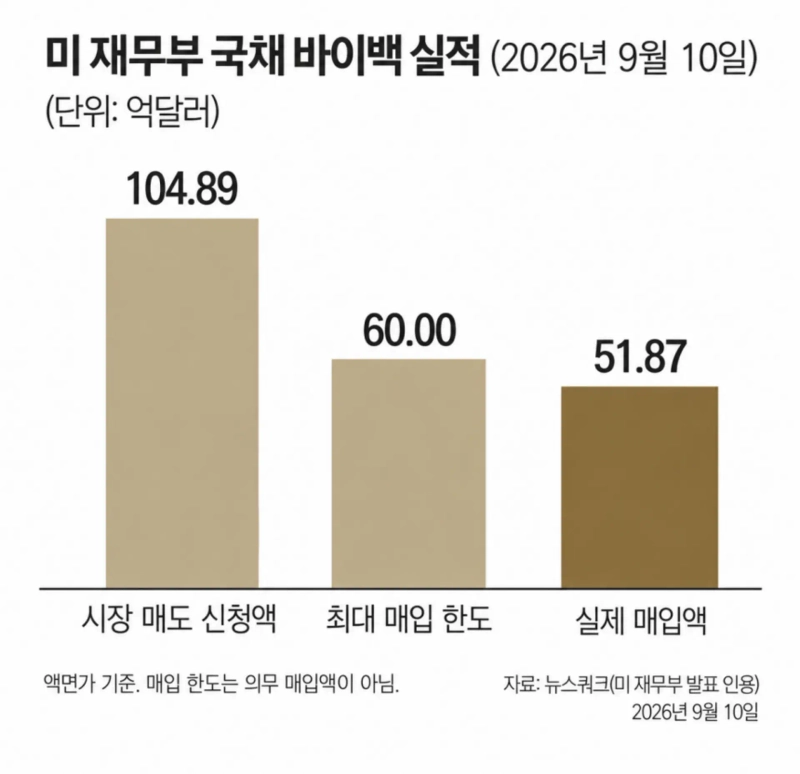
The US Treasury recently received offers to sell $10.489 billion of Treasuries, but bought only $5.187 billion. It could have purchased as much as $6 billion, yet did not use the full limit. The amount offered was nearly double the cap. The Treasury evaluates submitted securities based on market prices and relative value at the time, however, so it may choose not to fill the entire amount even when sell orders exceed the limit.
That underscores a key point: Treasury buybacks are not a policy of purchasing bonds indiscriminately to drive yields lower. The program is meant to support smooth market functioning, but the Treasury can decline to buy if it judges the price too high. Even so, the market had built up expectations that larger Treasury buybacks would lift bond prices and lower yields.
Actual Buyback Volume Reached 86%
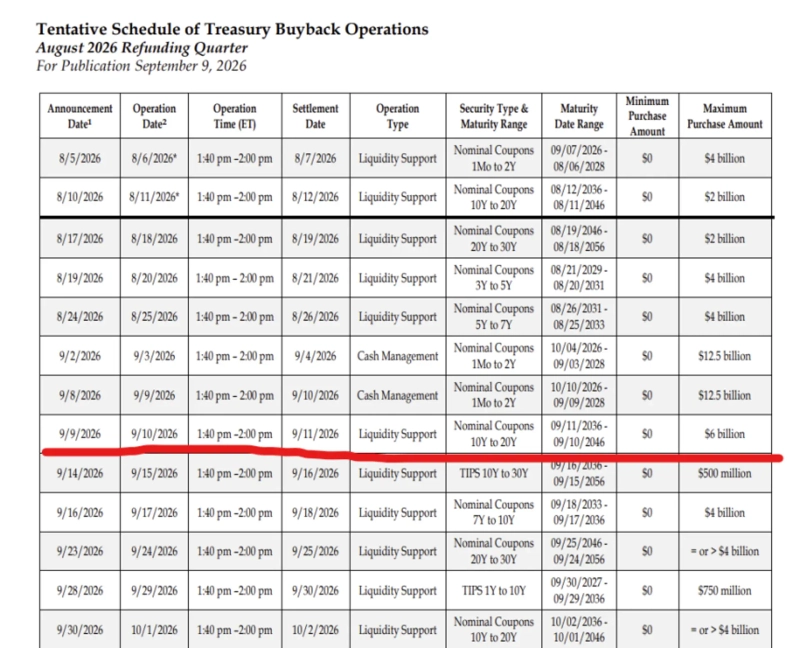
According to TreasuryDirect, the Treasury’s securities website, the Sept. 10 buyback targeted nominal Treasuries with 10 to 20 years remaining to maturity. The Treasury said it would buy as much as $6 billion and ended up purchasing 86.45% of that amount. The $6 billion figure, however, was based on face value. Because face value is the principal repaid at maturity, it can differ from the amount of cash the Treasury actually paid that day.
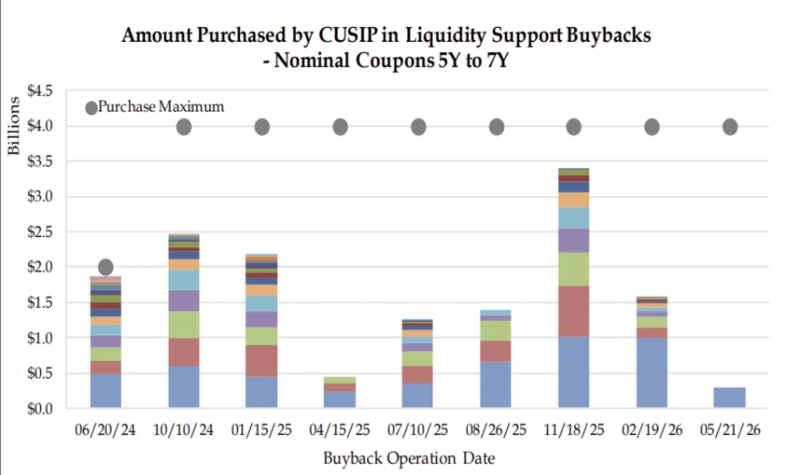
The Treasury screens submitted offers by looking at market prices and relative value. It does not automatically accept bonds simply because they are offered for sale, nor does it have to take securities priced too richly. Even if bids exceed the cap, the government is under no obligation to accept every price. That is why purchases coming in below the ceiling do not by themselves mean the operation failed.
Nellie Liang, the Treasury’s under secretary for domestic finance, explained in 2023 when the framework was being designed that “the goal is not to purchase a specific quantity of securities.” The mechanics help explain why the Treasury buys selectively. Newly issued Treasuries attract the most trading, while older issues, despite being backed by the same US government, can be harder to buy and sell. By purchasing those older securities regularly, the Treasury gives investors a way to turn them into cash.
That reduces the need for investors to slash prices when they need to sell quickly. Financial firms that intermediate bond trading can also sell Treasuries they hold to the Treasury and redeploy the proceeds elsewhere. If Treasuries become easier to trade, investors may demand less extra yield to compensate for the risk that they will be harder to sell later.
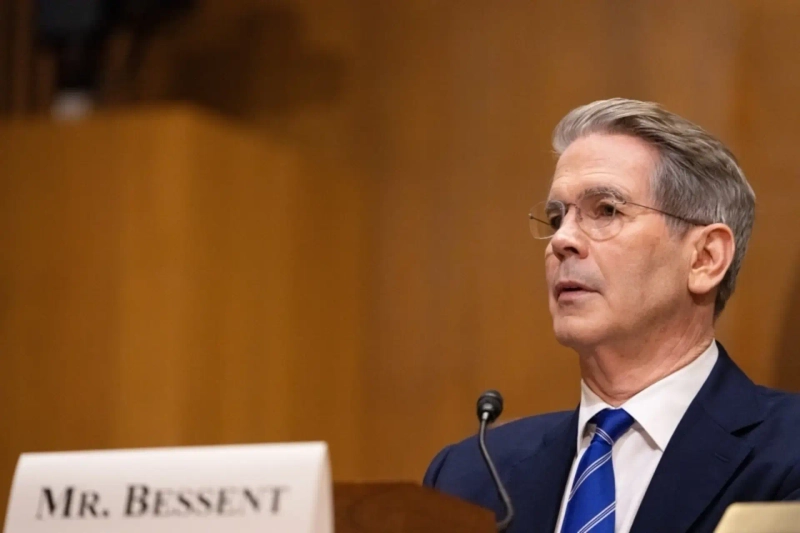
The Treasury itself does not appear to believe this buyback program gives it broad control over market yields. Treasury Secretary Scott Bessent recently said it “cannot change the equilibrium price.” Jim Barnes, a fixed-income director at Bryn Mawr Trust, also told Reuters that the $6 billion cap for this operation was not a large amount.
This purchase was the first case in which the Treasury applied its previously announced expansion of buybacks. Last month, it said it would raise the per-operation limit for purchases of Treasuries with 10 to 20 years and 20 to 30 years remaining from $2 billion to at least $4 billion. The higher cap applies from Sept. 9 through Nov. 4, when the Treasury will announce its next quarterly borrowing plan. In the Sept. 10 operation, the limit was increased to $6 billion.
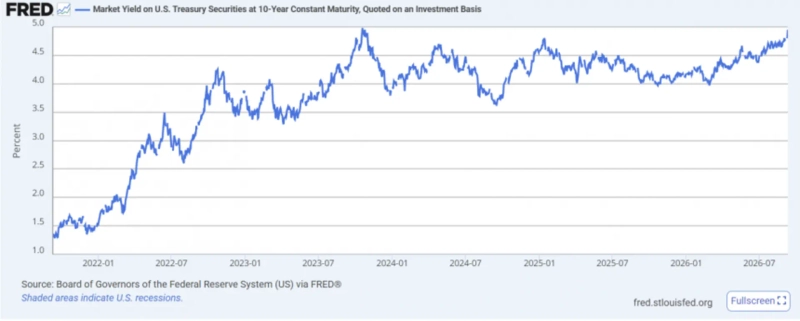
But a larger buyback cap did not immediately push long-term yields lower. Data from the St. Louis Fed’s FRED show the 10-year Treasury yield rose to 4.95% on Sept. 10 from 4.78% on Sept. 4. Over the same period, the 30-year yield climbed to 5.37% from 5.24%. That was an increase of 0.17 percentage point and 0.13 percentage point, respectively.
Did the Buyback Have Any Effect?
That does not necessarily mean the buyback had no effect at all. Reuters reported that the 10-year yield rose as high as 4.979% intraday on Sept. 11 before falling back to about 4.93%. A few days of rising yields are not enough to call the operation a failure. By the same token, a modest pullback afterward cannot automatically be credited to the buyback.
When the government buys back bonds, it does not create new money or reduce the fiscal deficit by the same amount. The Treasury must use cash on hand or raise funds by issuing new securities. The bonds it repurchases disappear in settlement, but if the money is raised by selling other Treasuries, it is hard to argue that the government’s overall debt burden has fallen. That makes the structure different from quantitative easing, in which the Federal Reserve buys Treasuries by creating new reserves.
ING said in a report last month that the Treasury can fund buybacks by issuing Treasury bills if needed. Whether it uses existing cash or sells more short-term bills can affect money markets in the near term. Either way, the government still has to find the money somewhere else.
Some argue that buying long-term bonds while funding those purchases with short-term debt merely shifts where the risk sits. A smaller stock of long-term Treasuries in the market may reduce some long-end duration risk. But the government would then issue more short-dated debt and have to refinance more often. If short-term rates remain high later, interest costs could rise further.
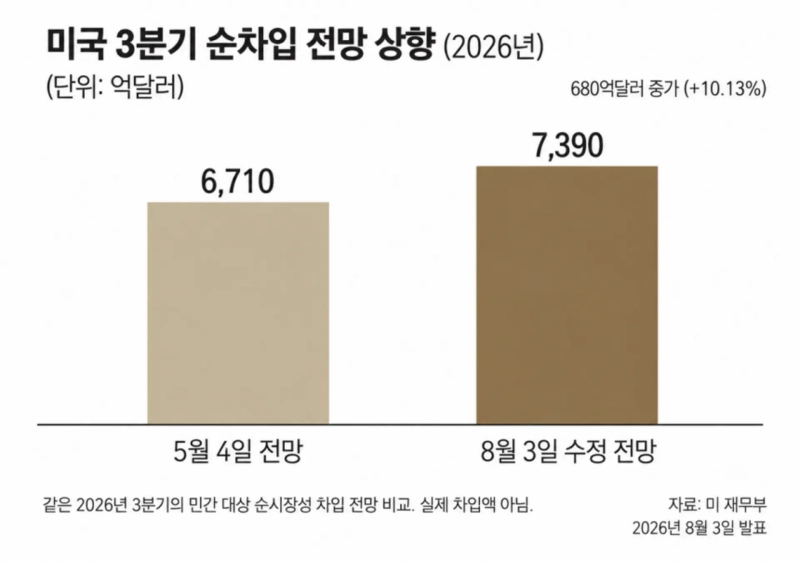
The government’s heavy borrowing needs are already clear. On Sept. 3, the Treasury projected net privately held marketable borrowing of $739 billion for the third quarter of this year. That was $68 billion more than its May estimate, largely because expected net cash inflows were lower. The figure covers net borrowing for the full quarter.
George Cole, Goldman Sachs’s head of European rates strategy, said in a webinar reported by Business Insider that fiscal concerns would not disappear. If markets remain worried about future US borrowing and bond supply, investors may still demand more compensation for locking up money over a long period, regardless of measures aimed at improving trading in some existing Treasuries.
Inflation is another factor. The August consumer price index released by the Bureau of Labor Statistics on Sept. 11 rose 0.4% from the previous month on a seasonally adjusted basis and 3.4% from a year earlier on an unadjusted basis. Energy prices rose 2.1% in the month, while gasoline climbed 3.9%. Gasoline accounted for more than a third of the monthly increase in overall consumer prices. Treasury buybacks cannot directly change energy supply or prices at the pump.
Jim Reid, a strategist at Deutsche Bank, told Reuters that geopolitical concerns were driving everything. Michael Metcalfe, State Street’s head of macro strategy, said underlying conditions had not changed.
That said, it would also be too simple to conclude the buyback had no effect whatsoever. The argument is that the program’s purpose is less about lowering yields directly and more about making trading work more smoothly.
ING said in last month’s report that after the Treasury announced an expansion of long-term buybacks, the 30-year swap spread narrowed by 4 basis points and then tightened by another 3 basis points. That suggests the relative pricing of long-term Treasuries improved versus interest-rate derivatives. Even if broader market yields rise, trading conditions and relative valuations for the bonds the Treasury is buying can still improve.
The US government has bought back its own debt before. The reasons then were different. Treasury records show that from March 2000 through April 2002, it conducted 45 buybacks totaling $67.5 billion. At the time, the government was running fiscal surpluses and issuing fewer new bonds. The main goal was to prevent liquidity in benchmark Treasuries from drying up and to put surplus government cash to use. That was a different backdrop from today, when the government must borrow heavily.
A commonly cited comparison is the Federal Reserve’s 2011 Operation Twist. At the time, the Fed said it would buy $400 billion of long-term Treasuries with 6 to 30 years remaining while selling an equal amount of Treasuries with maturities of three years or less. The objective was clear: to boost demand for long-term bonds, lower long-term yields and ease financial conditions.
In that sense, the current program is similar because it also involves buying long-dated Treasuries. But the Treasury’s recent buybacks are different in character. Their main purpose is to improve trading in older bonds and manage Treasury cash efficiently. Treating them like a policy tool aimed at lowering long-term yields, as in the Fed’s Operation Twist, could lead investors to overestimate both their impact and their durability.
How Higher Treasury Yields Affect Stocks
The first way higher US Treasury yields affect equities is through corporate valuation. Stock prices reflect the present value of the cash companies are expected to earn in the future. When the discount rate rises, the present value of those future profits falls. Companies whose valuations depend heavily on growth far into the future may be hit harder. Even so, if earnings prospects improve faster than rates rise, that can offset the pressure. Higher Treasury yields do not automatically mean technology stocks must fall.
The second channel is companies’ actual interest expense. Firms with ample cash and firms that need to borrow to invest do not feel the same impact from higher rates. A company that locked in long-term funding at low fixed rates in the past may not see its interest burden jump immediately even if market rates rise.
By contrast, companies facing large debt maturities and the need to refinance must absorb higher rates more directly. That is why investors need to look not only at total debt, but also at when it comes due and how much is fixed-rate versus floating-rate.
Korean investors also need to watch the exchange rate. If they bought US stocks or bonds without currency hedging, returns translated into won can fall even when the dollar price of the asset is unchanged, if the Korean currency strengthens. If the won weakens, the won value of dollar assets rises. Higher US rates do not automatically mean a stronger dollar. Anyone investing in US bonds needs to weigh both price risk from rate changes and won-dollar exchange-rate risk.
It also makes sense to consider several scenarios ahead. One is that inflation stays high and the US government’s heavy borrowing continues. In that case, long-term yields may not fall easily even if the Treasury expands buybacks and helps the market function more smoothly.
Another scenario is that energy prices and core inflation stabilize while the government’s funding burden also eases. If long-term yields fall under those conditions, that would more likely signal that borrowing costs are declining across the US economy.
There is also a scenario in which yields fall but the investment environment worsens. If recession fears grow, money may flow into safe-haven Treasuries and pull their yields down. At the same time, earnings expectations could deteriorate and corporate bond yields could rise. In that case, lower Treasury yields should not automatically be read as a positive signal for equities.
Kim Ju-wan, Korea Economic Daily reporter, kjwan@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.